Regulatory Framework Analysis
IRS Code Section 408(m): The Collectibles Rule Explained
Article by Steve Maitland | Research by: Victoria Maitland-Forshaw
Published: February 24, 2026 | Last Updated: September 29, 2026
Editorial Focus: Regulatory Framework for Precious Metals Allocations
For individuals researching self-directed retirement accounts, understanding the statutory framework governing asset placement is critical. Internal Revenue Code (IRC) Section 408(m) is the primary federal provision governing when an IRA's acquisition of a collectible is treated as a distribution and which coins and bullion fall within statutory exceptions. Readers can also review our guide to Gold IRA approved metals and our broader Gold IRA guide.
This review provides a structured breakdown of the statutory text, detailing the specific parameters under which physical metals meet regulatory inclusion criteria for IRA compliance. The Internal Revenue Service (IRS) administers enforcement of these provisions under the broader regulatory framework.
Part 1: The General Prohibition — IRC Section 408(m)(1)
Section 408(m)(1) outlines the primary restriction regarding physical assets in a retirement account. The code states that if an IRA acquires a "collectible," the acquisition is treated as a taxable distribution equal to the cost of the asset.
For account holders, this mechanism means that placing non-compliant assets into an IRA generally results in immediate tax liabilities and potential early distribution penalties, impacting the tax-advantaged structural characteristics of the account.
Part 2: Defining a Collectible — IRC Section 408(m)(2)
To clarify the restriction, Section 408(m)(2) explicitly defines what the Internal Revenue Service considers a collectible. The statutory definition includes:
- Any work of art
- Any rug or antique
- Any metal or gem
- Any stamp or coin
- Any alcoholic beverage
- Any other tangible personal property specified by the Secretary
Metals and coins generally fall within the statutory definition of collectibles unless one of the specific exceptions in Section 408(m)(3) applies. Those exceptions cover certain coins and qualifying bullion held in the required manner. See our guide to Gold IRA approved metals.
✓ Potentially Allowed Under Section 408(m)(3)
- • Gold bullion meeting the applicable exchange-delivery fineness test
- • Silver, platinum and palladium bullion meeting the applicable test
- • Certain coins specifically listed in Section 408(m)(3), including American Gold Eagles
✗ Generally Treated as Collectibles
- • Most pre-1933 historical coins
- • Most graded or numismatic coins outside a statutory exception
- • South African Krugerrands
Part 3: The Statutory Exceptions — IRC Section 408(m)(3)
Section 408(m)(3) provides exceptions for certain U.S. coins, coins issued under the laws of a state, and qualifying bullion. When the requirements are met, acquiring those assets is not treated as acquiring a collectible under Section 408(m)(1).
The Bullion Exception Explained
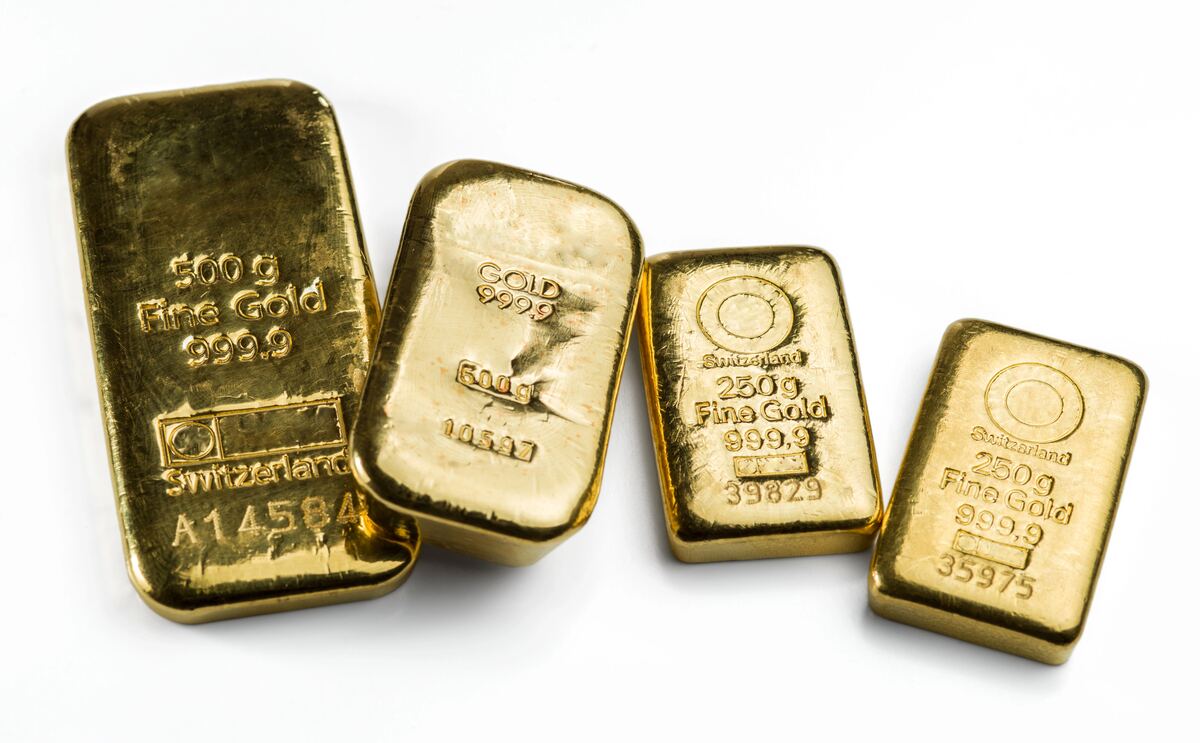
Section 408(m)(3)(B) covers bullion whose fineness equals or exceeds the minimum fineness required for delivery under a regulated futures contract, provided the bullion is in the physical possession of a qualifying trustee. Current CME Group delivery specifications commonly referenced for these metals include:
The bullion exception also requires physical possession by a trustee described in Section 408(a). In practice, IRA trustees or custodians may use third-party depositories while retaining the required custodial control. If the account owner instead takes personal possession, the bullion no longer satisfies the express possession condition in Section 408(m)(3)(B), and the transaction may be treated as a distribution.
Cross-Reference to 31 U.S.C. § 5112: The American Eagle Provision
Section 408(m)(3)(A) provides exceptions for specified U.S. coins described in 31 U.S.C. Section 5112, as well as coins issued under the laws of a state.
The American Gold Eagle is 22-karat gold and therefore falls below the .995 fineness commonly associated with the bullion exception. It can nevertheless qualify because the coin is among those specifically described in 31 U.S.C. Section 5112 and referenced by Section 408(m)(3)(A). Other coins are also covered by the statutory coin exceptions, so eligibility should be checked against the precise wording of Section 408(m)(3).
Why Specific Assets Do Not Meet Statutory Inclusion Criteria
Understanding these three subsections clarifies why the majority of global coins do not meet IRA qualification standards. When market participants research structural eligibility for asset inclusion, regulatory analysis indicates several structural reasons why a coin may not meet custodial acceptance standards:
Numismatic Value
Coins held for rarity, date, condition, or numismatic value generally remain within the collectible definition unless they fall within a specific statutory coin exception.
Insufficient Purity
Coins such as the South African Krugerrand and many pre-1933 U.S. gold coins do not meet the .995 bullion fineness threshold and are not among the federal coin categories expressly referenced in Section 408(m)(3)(A). They therefore generally remain collectibles for this purpose.
Authentication and Origin
Meeting a stated purity level is not the only consideration. The statutory test refers to the minimum fineness required for delivery under a regulated futures contract, and the bullion must also satisfy the trustee-possession requirement. Custodians may apply additional operational acceptance standards, but those policies should not be presented as requirements written directly into Section 408(m).
Because eligibility depends on the asset, the transaction structure and custody arrangements, investors should confirm the details with the IRA trustee or custodian before purchase. Readers comparing providers can review our assessment of the best Gold IRA companies, including fees, services and custody arrangements.
Interaction with IRC Section 4975: Prohibited Transactions
While Section 408(m) addresses collectibles, Internal Revenue Code Section 4975 defines prohibited transactions involving a plan and a disqualified person. These include certain sales, exchanges, loans, transfers or uses of plan assets, and acts of self-dealing.
For an IRA, the relevant disqualified-person rules can include the IRA's fiduciary and specified family members, including a spouse, ancestors, lineal descendants, and spouses of lineal descendants. The statute also covers certain entities and service providers. Key considerations include:
- Sale or Exchange: Selling personally owned metal to one's own IRA may constitute a prohibited sale or exchange between the plan and a disqualified person.
- Loans and Personal Use: IRA assets cannot be lent to, pledged for, or used for the benefit of a disqualified person outside a permitted distribution.
- Personal Possession: Taking control of IRA-owned bullion can defeat the trustee-possession requirement in Section 408(m)(3)(B). Depending on the facts, it may also raise prohibited-transaction concerns and cause taxable-distribution consequences.
Trustee and Custodian Qualification Requirements
Under IRC Section 408(a)(2), the IRA trustee must be a bank as defined in Section 408(n), or another person that demonstrates to the IRS that it can administer the trust consistently with Section 408. Nonbank trustees and custodians must obtain IRS approval. Our custodian due-diligence checklist explains practical checks for investors.
The IRS approval process for a nonbank trustee or custodian examines continuity, fiduciary experience, financial responsibility, accounting capacity, fitness to handle funds, fiduciary conduct, bonding, net worth and auditing controls. Precious-metals IRA custodians commonly coordinate storage through third-party depositories. Readers can compare provider services and custody arrangements in our review of the best Gold IRA companies.
Further reading: Compare the services, fees and custody arrangements discussed in our assessment of the best Gold IRA companies.
Required Minimum Distribution (RMD) Implications
Traditional IRA owners are generally subject to Required Minimum Distributions beginning at the applicable statutory age; Roth IRA owners generally are not required to take lifetime RMDs. Physical assets can make valuation and distribution more operationally complex than cash or publicly traded securities.
- Valuation Requirements: An IRA RMD is generally calculated using the account balance at the end of the immediately preceding calendar year and the applicable IRS distribution period. The trustee or custodian reports the IRA's year-end fair market value.
- Cash Distribution: Metals may be sold within the IRA and cash distributed, subject to the custodian's procedures and transaction terms.
- In-Kind Distribution: If the custodian permits an in-kind distribution, the metal is delivered out of the IRA. The fair market value of the noncash property is included in the reportable distribution, generally on Form 1099-R.
Analysis of Common Structural Misinterpretations
Given the complexity of IRC Section 408(m) and its intersection with other tax codes, structural misunderstandings frequently emerge in public discourse. Comparative research highlights three prevailing misinterpretations:
Myth: "All sovereign gold coins qualify for IRA inclusion."
Regulatory Reality: Sovereign status does not guarantee compliance. Coins such as the South African Krugerrand or the UK Sovereign are minted by national governments but fail the .995 fineness test and lack an explicit statutory carve-out, rendering them prohibited collectibles.
Myth: "The Home Storage IRA framework is compliant."
Regulatory Reality: Section 408(m)(3)(B) expressly requires qualifying bullion to be in the physical possession of a trustee described in Section 408(a). In McNulty v. Commissioner (2021), the Tax Court held on the facts before it that an IRA owner's unfettered control and personal possession of American Eagle coins resulted in taxable distributions. The decision does not make every advertised arrangement identical, but it is a significant warning against owner-controlled home storage. See our scam protection framework.
Myth: "22-karat coins are universally approved."
Regulatory Reality: Karat rating alone does not determine eligibility. American Gold Eagles can qualify through the specific coin exception, despite being 22-karat, but all coins must be assessed against the statutory categories in Section 408(m)(3).
Editorial Research & Verification Record
| Statutory / Regulatory Claim | Verification Status |
|---|---|
| IRC § 408(m)(2) Collectible Definitions | ✓ Statutory Text Reviewed |
| CME Group Exchange-Delivery Fineness Specifications | ✓ Exchange Specifications Reviewed |
| 31 U.S.C. § 5112 American Eagle Exemption | ✓ Statutory Text Reviewed |
| IRC § 4975 Prohibited Transactions & Self-Dealing | ✓ Statutory Text Reviewed |
| McNulty v. Commissioner (157 T.C. No. 10) Owner-Controlled Possession | ✓ Tax Court Decision Reviewed |
| Form 1099-R In-Kind Distribution Reporting | ✓ IRS Reporting Guidance Reviewed |
Frequently Asked Questions: IRC 408(m)
What is IRS Code Section 408(m)?
Internal Revenue Code Section 408(m) provides that an IRA's acquisition of a collectible is generally treated as a distribution and sets out exceptions for specified coins and qualifying bullion held by a trustee described in Section 408(a).
Are all gold coins allowed in an IRA?
No. Coins generally fall within the collectible definition unless they are covered by a specific coin exception or qualify as bullion under Section 408(m)(3)(B), including its fineness and trustee-possession requirements.
Can I store Gold IRA metals at home?
Section 408(m)(3)(B) requires qualifying bullion to be in the physical possession of a trustee described in Section 408(a). The Tax Court's McNulty decision also found taxable distributions where the IRA owner had unfettered control and personal possession of coins. Investors should obtain qualified tax advice before relying on any home-storage arrangement.
Summary of the Compliance Framework
For individuals examining precious metals for retirement allocations, IRC Section 408(m) establishes the following framework:
- ✓ Sections (1) and (2) generally treat an IRA's acquisition of a collectible as a distribution and define the collectible category.
- ✓ Section (3) provides exceptions for specified coins, state-issued coins and qualifying bullion.
- ✓ Bullion possession requirement requires qualifying bullion to be in the physical possession of a trustee described in Section 408(a).
Because Section 408(m) operates within a broader statutory framework, any future amendment to purity thresholds or collectible definitions would directly alter retirement account eligibility standards. Ongoing statutory review remains essential for accurate classification.
Disclaimer: This research article is provided for informational and educational purposes only and does not constitute investment, tax, or legal advice. Maitland Wealth does not provide investment advisory services. Readers should consult a qualified financial professional or tax attorney regarding their specific IRA circumstances. Please review our Disclaimer page for additional information.